

Strive’s SATA perpetual preferred stock has returned to its $100 par value, closing at $100.01 on August 21, 2026, after briefly trading just below the level the prior session. The move reactivates the company’s at-the-market (ATM) issuance channel and has already translated into substantial Bitcoin purchases.
According to BitcoinTreasuries.net SATA accumulation tracker data, the two sessions produced an estimated combined 440.56 BTC. On August 20, SATA closed at $99.89 (11 cents below par) with $54.51 million in daily volume, generating an estimated $16.31 million in net ATM proceeds from roughly 167,300 shares issued and translating into approximately 225.62 BTC at an average Bitcoin price of $72,283. The following day, SATA closed at $100.01, volume totaled $44.63 million, net proceeds reached an estimated $16.59 million from about 170,100 shares, and the program added roughly 214.94 BTC at an average Bitcoin price of $77,189. Combined net ATM proceeds across the two days stood at approximately $32.90 million on 337,400 shares issued, with total volume of $99.14 million.
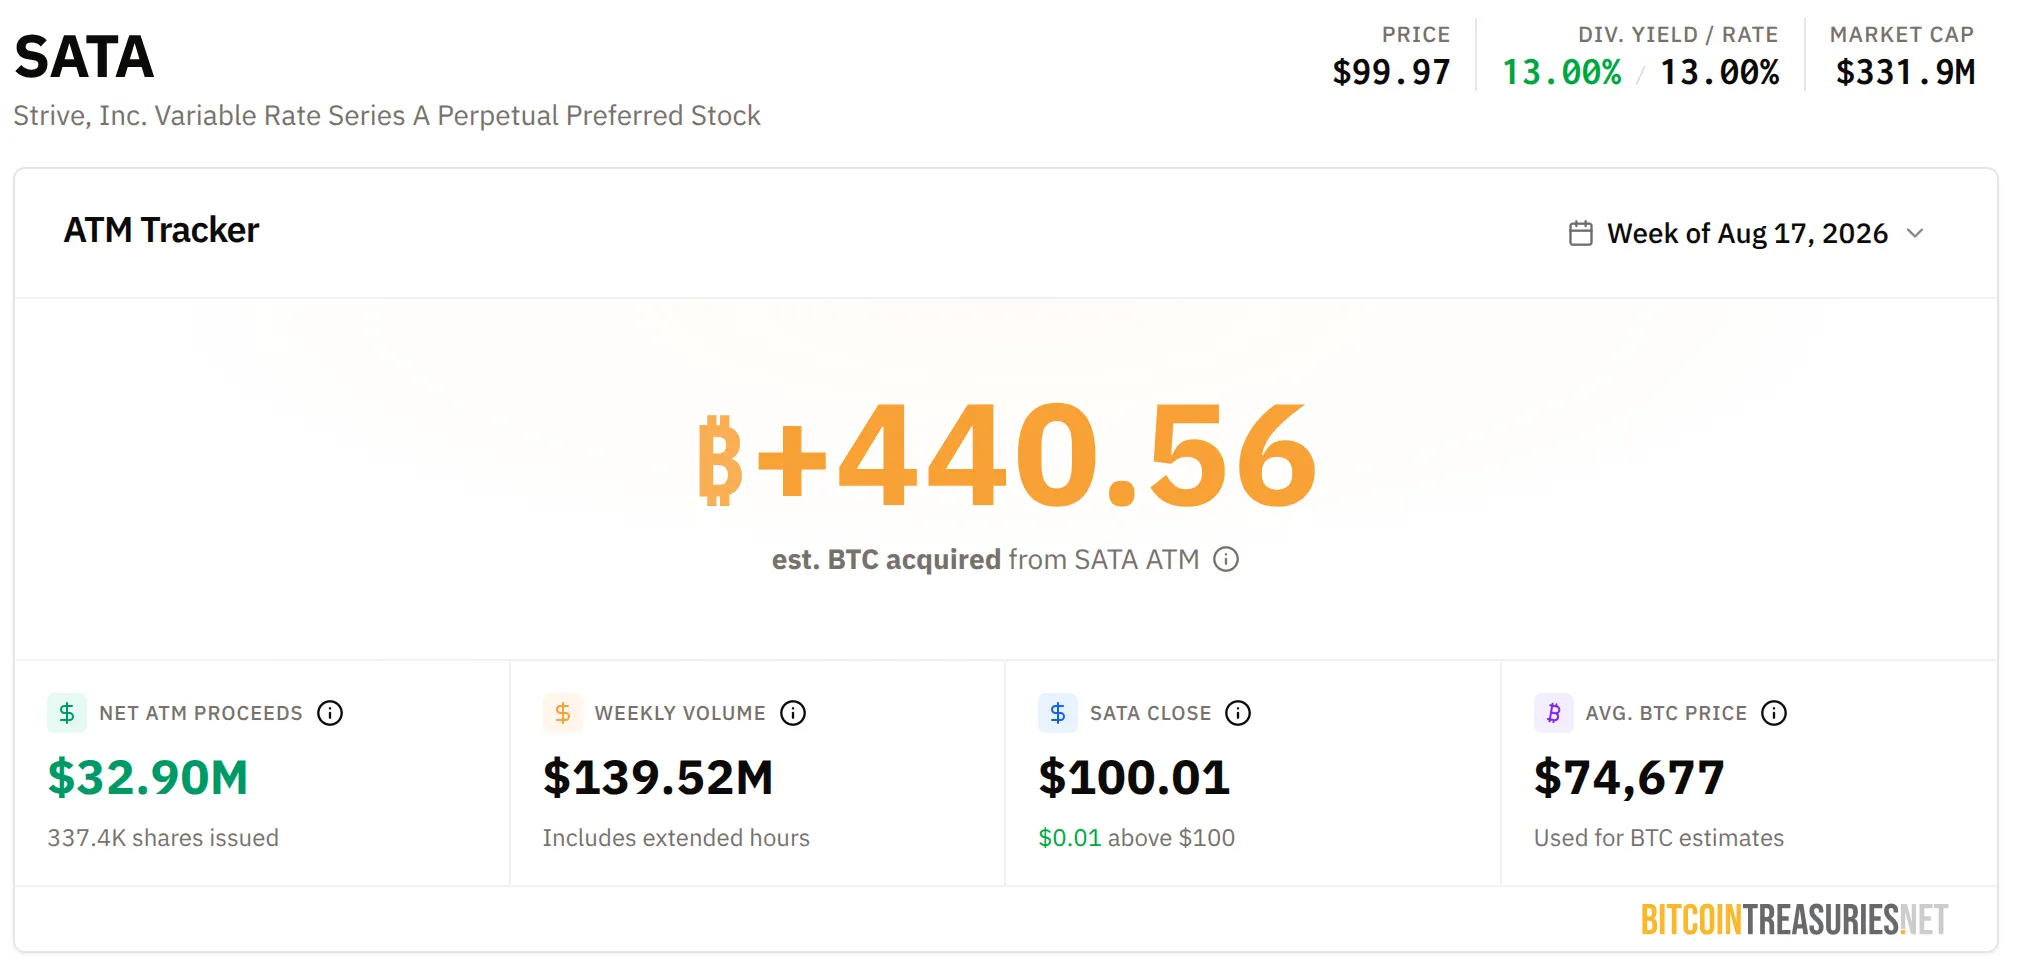
This marks a meaningful restart of SATA-driven accumulation after a multi-month pause. The instrument—Strive’s Variable Rate Series A Perpetual Preferred Stock—functions as a high-yield digital credit product designed to trade near its $100 stated amount. It currently carries a 13% annualized dividend paid every business day, a structure introduced in mid-June 2026 that made SATA the first U.S.-listed security to distribute cash dividends daily. Strive targets a $99–$101 trading range and uses the variable-rate mechanism to help anchor the price; when the stock trades at or above par, the company can issue new shares efficiently and deploy the capital into Bitcoin.
The June Crash and Recovery
SATA’s return to par follows a sharp dislocation in June 2026 that tested the young digital-credit category. On June 18, amid a broader leverage-driven selloff that also hit Strategy’s STRC, SATA fell from near-par levels to an intraday low of $92.88 before closing at $97.71 on elevated volume of more than 1.6 million shares. Strive CEO Matt Cole described it as “the most difficult day in the history of Digital Credit,” emphasizing that the move reflected forced liquidations by leveraged investors rather than any deterioration in credit quality or dividend coverage. Reserves remained intact.
The pressure continued in subsequent sessions. SATA closed at $83.53 on June 25 and printed an all-time low of $79.01 intraday on June 26—below its original IPO price of $80 from November 2025. At those levels the effective yield on the 13% coupon rose well above 16%. The selloff was widely attributed to margin calls cascading through positions that had treated the preferreds as relatively stable collateral, not to any change in Strive’s debt-free balance sheet, Bitcoin holdings, or ability to service the preferred dividends.
Recovery was gradual but steady. Through July the stock climbed back into the mid-to-high $90s. By mid-August it was consistently testing the $99.50–$99.90 zone, its closest approach to par since the mid-June episode. Income-oriented buying, the daily dividend feature, and relative resilience of Strive’s Bitcoin-backed structure supported the rebound even as STRC continued to trade at a more noticeable discount. The August 21 close above $100 completed the recovery and reopened the ATM flywheel.
Treasury Impact and Context
Strive has grown its Bitcoin holdings aggressively since launching SATA. From low-thousands of BTC in late 2025, the company reached approximately 20,246 BTC by mid-August 2026 through a combination of open-market purchases, earlier SATA proceeds, and other capital-markets activity. It remains debt-free, with significant cash and marketable securities (including a position in Strategy’s STRC) reserved to support the preferred dividends. The latest estimated 440 BTC addition further expands the treasury that underpins SATA’s credit profile.
The product continues to serve as the primary alternative digital-credit instrument to Strategy’s STRC. Both are designed to offer high cash yields while the issuers underwrite Bitcoin volatility on the balance sheet. SATA’s daily payment schedule and Strive’s clean capital structure differentiate it, though liquidity remains thinner than STRC’s. Management has long framed the $100 level as the strategic inflection point: above it, equity capital can be raised and converted directly into Bitcoin, improving BTC-per-share metrics over time.
Whether SATA can sustain trading at or above par—and thereby enable repeated ATM issuance—will determine how quickly the accumulation flywheel turns in the weeks ahead. Bitcoin price strength, continued demand for the 13% daily-yielding instrument, and the broader health of the digital-credit market will all play roles. For now, the return to par and the estimated 440 BTC purchase demonstrate that the mechanism is functioning as designed after a severe but temporary dislocation.
Want more bitcoin treasury coverage in your search results? Add Bitcoin Treasuries as a preferred source on Google.